The Process of Repossessing Property
📅 2026 Update: Changes in Repossession Processes
Since the original article was written, several important changes have occurred in the process of repossessing property in the U.S. These changes affect how repossession is handled, including fees, eligibility, and procedures. The earlier article continues further down the page.
🔍 Recent Trends in Repossession
The trend in property repossession has shifted towards more transparent processes. Many states are now implementing new regulations to protect homeowners. This means lenders must give clearer information about the repossession process.
- 📜 Increased Disclosure: Lenders must now provide borrowers with more detailed information about their rights.
- ⏳ Extended Timelines: Some states have increased the time required before a lender can begin repossession. This gives homeowners more time to find solutions.
💰 Changes in Fees
Fees associated with repossession have also changed. It’s essential to understand these costs.
- 🏷️ Standardized Fees: Some states are standardizing fees for repossession services, which can help borrowers avoid unexpected charges.
- 📈 Potential Cost Increases: In some areas, fees may have increased due to higher service costs.
📜 Legal Eligibility Requirements
The legal requirements for repossession have become more stringent in many regions.
- 🔑 Eligibility Criteria: Homeowners must meet specific criteria before a lender can initiate repossession. This includes being in default on their mortgage payments.
- ⚖️ Documentation: Lenders are now required to provide proof of default and follow strict guidelines before proceeding with repossession.
🤝 Resources for Homeowners
Homeowners facing repossession can find help through various resources.
- 🏠 Nonprofit Organizations: Many nonprofits offer assistance to homeowners in danger of repossession. They provide counseling and resources.
- 📞 Hotlines: Some states have established hotlines to help homeowners understand their rights and options.
📌 Key Points to Remember
- 🏡 New regulations aim to protect homeowners during repossession.
- 💵 Fees are becoming more standardized but can still vary by state.
- 📜 Eligibility requirements for repossession are stricter now.
- 🤝 Resources are available for those facing repossession issues.
💡 Tips for Navigating Repossession
Reviewing the specifics of your situation with an attorney is crucial for understanding your rights.
📖 Understand Your Rights
Homeowners should familiarize themselves with their rights during the repossession process. Knowing your rights can help you respond effectively.
⏳ Act Quickly
If you receive a notice of default, it’s important to act quickly. Delaying may limit your options for negotiation or repayment plans.
📝 Keep Records
Maintain detailed records of all communications with your lender. This documentation can be vital if disputes arise during the repossession process.
🤝 Seek Help Early
Do not hesitate to reach out to local nonprofits or housing organizations. They can offer guidance and resources to assist you.
📞 Consider Mediation
In some cases, mediation can help you negotiate a solution with your lender. This can be a less confrontational way to address repossession issues.
📅 Stay Informed
Keep up with changes in property law and repossession processes in your state. Laws can change, and being informed can help you navigate your situation.
🏆 Free Options Ranked by User Reviews (2026)
No national paid service in this area met the review threshold for assistance with repossession. This section lists free government and nonprofit resources.
🥇 1. HUD-approved Housing Counseling Agencies
HUD-approved agencies provide free counseling to homeowners facing repossession. They help individuals understand their options and develop plans to avoid foreclosure.
These agencies offer resources tailored to your specific financial situation. They can guide you through the process and connect you with local programs.
🥈 2. Legal Aid Services
Legal aid organizations offer free legal assistance to low-income individuals. They can help you understand your rights and represent you in disputes related to repossession.
These services are typically based on income and need. They focus on helping those who may not afford private legal counsel.
🥉 3. State Housing Finance Agencies
Many states have housing finance agencies that offer programs to assist homeowners. These can include financial assistance, counseling, and information on avoiding repossession.
These agencies often have programs specifically designed for those at risk of losing their homes. They can provide valuable support and resources.
4️⃣ Community Action Agencies
Community action agencies provide services to low-income individuals and families. They often include housing assistance programs aimed at preventing repossession.
These agencies can help with budgeting, financial planning, and finding resources to keep your home.
5️⃣ Local Nonprofit Organizations
Local nonprofits often focus on housing stability and can provide various services. They may offer legal help, financial counseling, and support groups for those facing repossession.
These organizations are vital resources in your community. They are dedicated to helping individuals navigate housing challenges.
🔎 What to Check Before Paying for Help
- 📄 Verify the organization’s credentials before engaging their services.
- 🔍 Look for reviews or testimonials from other users.
- 💬 Ask about fees upfront to avoid unexpected costs.
- ⏳ Understand the services offered and ensure they meet your needs.
❓ Frequently Asked Questions
🤔 What is the repossession process?
The repossession process generally involves the lender taking back the property after the borrower defaults on payments. This can vary by state, but it usually includes a notice of default.
🏠 How can I avoid repossession?
You can avoid repossession by communicating with your lender early. Exploring options like loan modification or repayment plans can also be beneficial.
📜 What happens after a property is repossessed?
After repossession, the lender typically sells the property to recover the owed amount. This sale can occur through various methods, including auctions.
💰 Are there fees involved in repossession?
Yes, there can be fees associated with repossession, such as legal fees and costs related to the sale of the property. These fees can vary by state.
📅 How long does the repossession process take?
The repossession process can vary in length, often taking several months. This timeframe depends on state laws and the lender's actions.
👥 Can I negotiate with my lender?
Yes, negotiation with your lender is possible. They may be willing to work with you on a repayment plan or other solutions to avoid repossession.
⚖️ Recent Cases Related to Repossession
Recent court rulings have clarified various aspects of the repossession process, affecting both lenders and borrowers. These rulings help define rights and responsibilities during repossession.
- Texas Court dismisses eviction appeal as moot in Bradley caseTexas Court of Appeals, 4th District (San Antonio) · May 20, 2026
- Texas Court Reverses Divorce Property Division in AppealTexas Court of Appeals, 3rd District (Austin) · May 22, 2026
- Court Reinstates HSBC Bank's Foreclosure Case Against KeelingAppellate Division of the Supreme Court of the State of New York · May 21, 2026
- Court upholds foreclosure ruling against Aliperti in NY caseAppellate Division of the Supreme Court of the State of New York · May 20, 2026
Browse more rulings on the news page to explore recent decisions that may impact this topic.
End of October 2026 Update
Repossession is the act of repossessing a given piece of property which was used as collateral for a given loan, or that was rented or leased, instead of being sold in its entirety. Repossessed property, then, is the property which is taken back by the repossessing party. In understanding the basic nature of repossessed property, it is important to comprehend that there is a difference between repossessed property and other forms of collateral.
For something to be considered repossessed property, that piece of property must always have been owned by the party that eventually repossesses the property. This is very significant, as property over which a given party has the right of ownership cannot be repossessed by another party. Repossessed property is specifically property that is taken back by the party that has full rights to that property.
Repossessed property is taken back normally because the possessor (not the owner/repossessor) failed to make some payment according to the plan associated with the repossessed property.
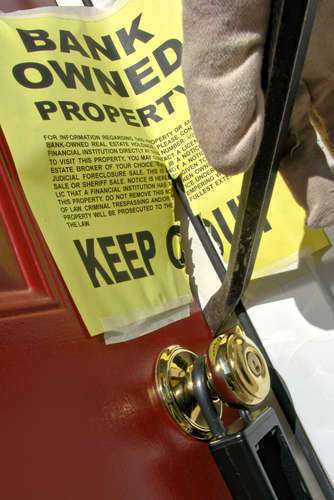
In such cases, the owner/repossessor may repossess the property without needing any kind of court injunction, as it has full rights to the repossessed property. The party taking back the repossessed property will likely sell that property in order to make the money which the possessor had not paid within the deal for the property.